

This latest round-up again includes some free sample items - but the wider press coverage of Clubland is reserved for paying members. It remains the best way to keep informed about clubs making the news worldwide.
The Times of London reported yesterday on financial setbacks for the group running the Arts Club in London’s Mayfair. What was historically a members’ club founded in 1863 has in recent years become a proprietary club, aimed less at the bohemian-but-impecunious artists who traditionally made up the Club’s membership, and aimed more at HNWIs in Mayfair, with its offering including a basement nightclub and a state-of-the-art “wellness clinic” from Lanserhof.
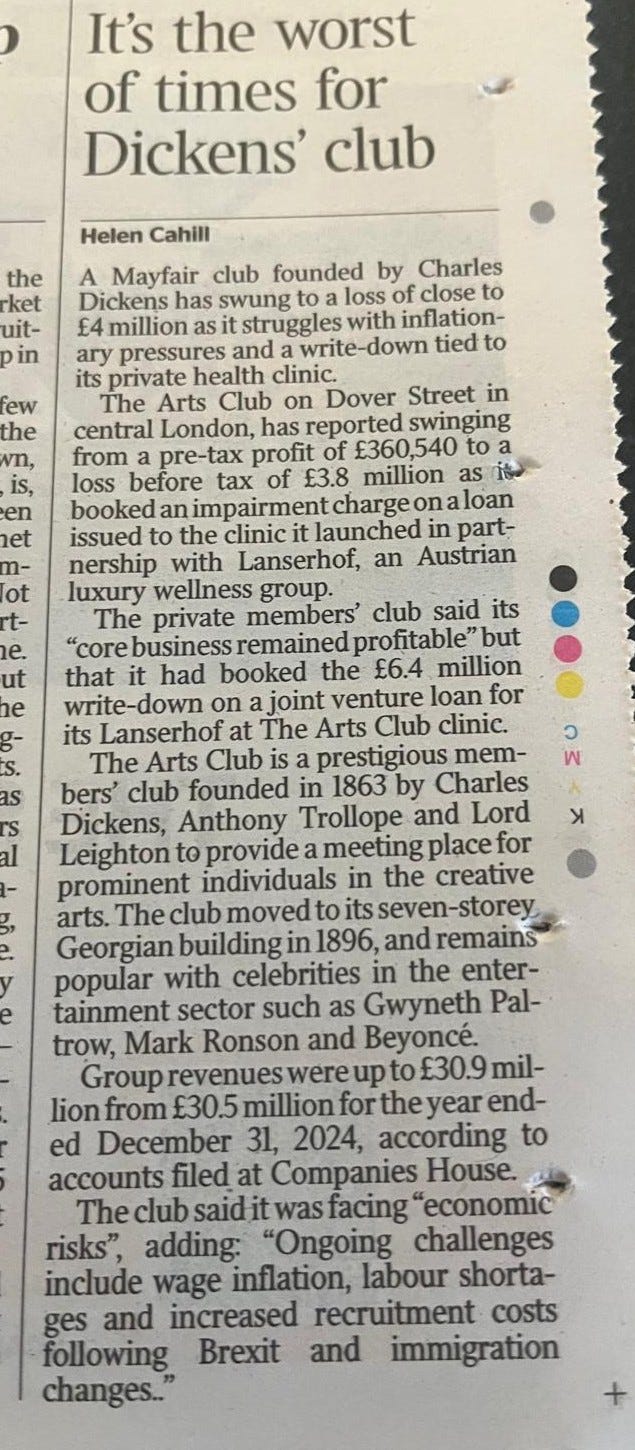
While the report does not necessarily reflect the full financial outlook for the group - which continues to operate a highly profitable branch in Dubai, that opened in 2020 - it does highlight some of the risks facing modern clubs, which I have previously highlighted.
The story was also covered by City AM, which noted:
“The Mayfair townhouse home to the club was sold for £90m in 2016 by a consortium led by [the Club’s current owners] property developer Gary Landesberg and Arjun Waney, the co-founder of fashionable London restaurants Roka and Zuma. The club has a 25-year lease and was not affected by the purchase.”
The recent boom in Mayfair clubs has created stiff competition among those clubs that are keen to attract a clientele of wealthy new members, and this is characterised by a “race for facilities”, as they often hope that state-of-the-art amenities such as wellness suites and comprehensive conciergeries will attract members paying significantly higher fees.
This high-spend-and-high-borrowing strategy comes with high risk, however. Such HNWIs and UHNWIs are not necessarily always seeking a traditional club experience, with everybody on the same level as their fellow members. Instead, the appeal of these management-led clubs can be predicated on offering a tailor-made experience with “the best” and “the latest” - which is necessarily transient. By definition, it is not a strategy that is likely to attract “lifers” (people who join a club with the intention of staying for life), and it is not intended to inculcate any of the wider sense of compromise or give-and-take (“We” rather than “I”), which characterises the most robust members’ clubs; but instead runs a high risk of appealing to dilettantes, who may lose interest and rapidly move onto the next fashionable thing.
Since the economics of clubs are based on steady, dependable, long-term membership subscriptions (and the financial planning and cross-subsidy that enables), the debt-fuelled “race for facilities” approach can be an existential threat to the very viability of the club model - not something which is always apparent when looking at glossy launch brochures. It would be unfair to single out the Arts Club, which is certainly not the only case of a club which has leaned in this direction in recent years. But it does not appear to me surprising to see such a story.
Talking of modern clubs carrying substantial debt, Soho House’s buy-out deal went through this week - though it looked for a while like it might not happen at all, after experiencing unexpected last-minute complications.
After an unhappy experience as a publicly-listed company since 2021, the club chain had announced in August 2025 that it was going to return to private ownership as part of a buy-out. The Financial Times had argued that it was not so much a buy-out:
“it’s mostly a take-private by existing shareholders. Large investors, chief among them Ron Burkle and the Yucaipa Companies, will roll their stakes into the new enterprise, padded with a relative sliver of equity from Apollo Global Management, MCR Hotels and Hollywood star and tech investor Ashton Kutcher.”
Last week, The Times of London reported that one of the major external investors in this “take-private”, MCR Hotels, had looked set to pull out of the deal. Under the headline, “Soho House shares drop as investor unable to fund $200m deal”, The Times noted:
“A key investor in the $1.8 billion deal to take Soho House private has pulled out of a $200 million funding commitment, putting the plan in jeopardy…MCR, a cornerstone investor, would not be able to deliver its multimillion-dollar equity commitment by the expected closing date.
“Shares in the business, which has expanded its portfolio to 46 clubs around the world, have fallen by around 40 per cent since they floated at $14 a share five years ago. On Thursday the stock was $1.48, or 16.4 per cent lower, at $7.47 by lunchtime in New York.
“In August, a consortium of investors led by New York-based MCR Hotels, which owns the High Line hotel in New York and the BT Tower in central London, agreed to take over the London-based private members’ club by paying $9 a share to acquire the rest of the company’s shares not held by four existing shareholders. They are rolling over their holdings as part of the deal.
The Times had approached MCR for comment.
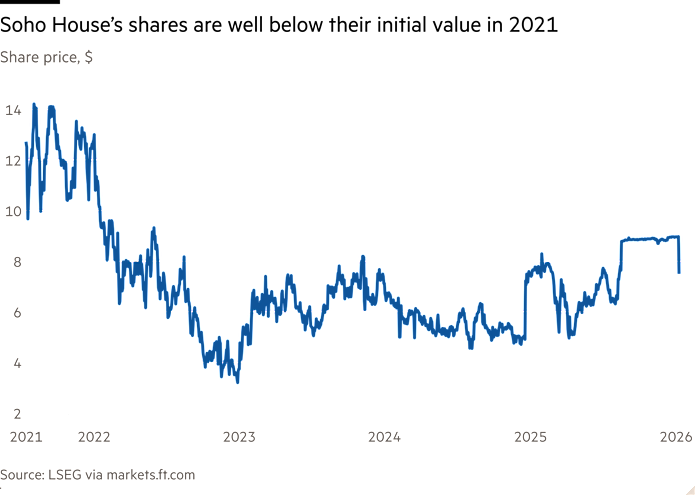
The Financial Times contextualised the share value of the Soho House Group, against the uncertainty around the take-private deal.
Yucaipa, the investment firm of Soho House’s billionaire executive chairman and controlling shareholder Ron Burkle, said in a regulatory filing that they:
“are engaging with affiliates of MCR, as well as other parties, to secure the funding. While numerous options are being pursued, there can be no assurance that such efforts will be successful.”
The Financial Times thought that the “take-private [was] at risk” from the news.
In the end, Soho House’s management was able to salvage the deal and plug the $200 million funding gap at the last minute, through a combination of MCR still providing some funding - but only around half their original proposed investment - as well as other investors taking on extra debt.
Hospitality Investor announced “Soho House scrapes together the cash to finally go private,” and that:
“After a nail-biting few days where it looked like the whole go-private deal might collapse, Soho House has secured the alternative funding needed to exit the public markets, according to a U.S. Securities and Exchange Commission filing on Wednesday.”
The Caterer recorded how the deal was finalised:
“The London-based members’ club partially covered the shortfall by entering into a $50m (£37m) equity commitment with Morse Ventures, owned by Tyler Morse, the chairman and chief executive of MCR Hotels affiliate MCR Investors.
“MCR Hotels itself has also committed a further $50m (£37m), taking its financing to $100m (£75m) – half of its original $200m figure.
“To raise the rest of the funding, Soho House’s debt financiers Apollo Capital Management and Goldman Sachs (GS Principal Investors) agreed to increase the members’ club’s unsecured notes facility from $150m (£112m) to $220m (£164m). Apollo also agreed to reduce its existing $50m equity commitment to $30m (£22m).
“Completing the financing measures, Soho House amended its existing rollover and support agreements with a number of shareholders, including Ivy Collection boss Richard Caring, who agreed to roll over additional shares rather than cash them out at the deal’s $9 (£7) a share price. This reduced the funds required to close the transaction by approximately $50m.”
The Wall Street Journal reported that after the announcement of the deal being salvaged, Soho House’s shares experienced a partial recovery, though were still down on their recent value:
“The stock climbed 12.8% to $8.93 in after-hours trading Wednesday. Through the close, shares were down 10.5% over the past three months.”
The story was also covered by Finimize, Hotel Investment Today, MCA Insight, Skift and Trefis.
The rest of the press round-up below continues to be a feature for paying subscribers only.
This fortnight’s edition contains 12 more stories drawn from 17 outlets worldwide.
If you are enjoying the Clubland Substack, do consider supporting my work as a paying subscriber - it means I can justify setting aside more of my time to bring you more material. And because of extra features like the below, my paying subscribers are some of the most informed people in Clubland.
